Introduction
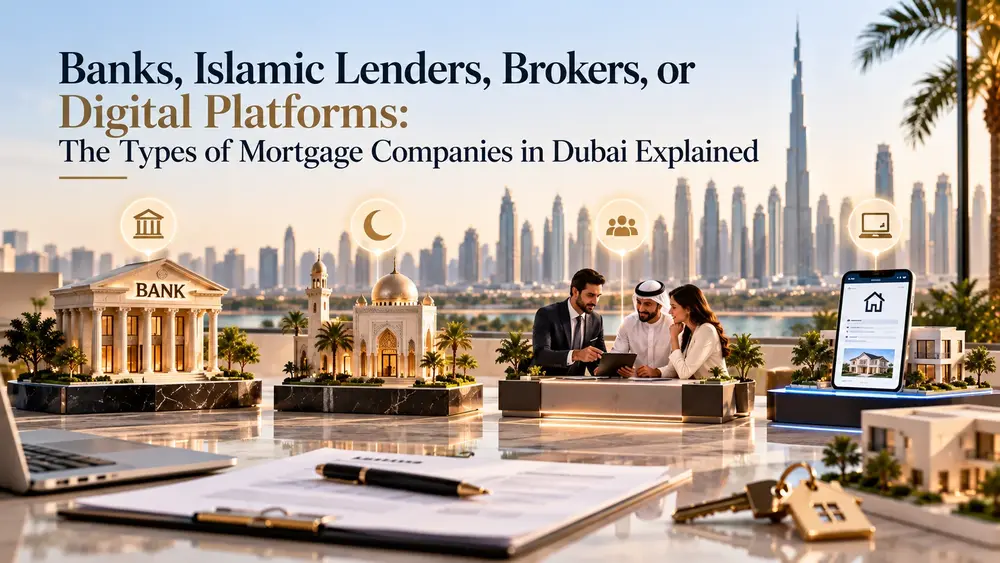
Search for a home loan in Dubai and you will see a long list of names. Some are banks. Some are advisers. Some are apps that promise an answer in minutes. They all appear in the same search results, but they do very different jobs. Understanding the different mortgage companies in Dubai helps you know who actually lends the money, who gives advice, who pays whom, and whose interests each one serves. This blog explains the main types, their strengths and weaknesses, and how to choose the right one for your situation.
Why the Type of Company Matters
The short answer is this: banks lend, brokers compare and negotiate, and digital platforms speed up the comparison. Each type earns money differently, and that affects the advice you receive.
A bank wants you to take its own product. A broker is usually paid a commission by the bank you choose, so a good one has a reason to find you a loan that gets approved. A digital platform may be a broker with a website in front of it. Knowing which is which helps you ask the right questions from the start.
Conventional Banks
Local and international banks are the main lenders in the market. Most offer a choice between a fixed rate for one to five years and a variable rate linked to EIBOR, the benchmark rate banks use to price loans, plus a set margin.
The main strengths of going to a bank directly:
- You may get perks if you already move your salary to that bank
- You deal with the lender itself, with no middle step
- Some banks run special offers for existing customers
The main weakness is simple. A bank can only show you its own products. Branch staff cannot tell you if another bank would give you a lower rate or approve a larger amount.
Islamic Banks and Islamic Finance Windows
Islamic home finance follows Sharia principles, so it does not charge interest. Instead, the bank earns a profit through structures such as Ijara (lease to own), Murabaha (cost plus profit), or Diminishing Musharaka (shared ownership that you gradually buy out).
Many people are surprised to learn that Islamic home finance is often priced against EIBOR too. This means the monthly cost can be very close to a conventional loan. Several conventional banks also offer Islamic home finance through a separate division. The same Central Bank loan-to-value limits apply to both types.
Mortgage Brokers and Consultancies
Brokers do not lend money. They compare offers across a panel of banks and match each buyer to the lenders most likely to approve them on good terms. They also prepare your documents, negotiate pricing, and chase the bank for updates.
Before you choose a broker, ask:
- How many banks are on your panel?
- Are you paid by the bank, by me, or both?
- Do you handle cases like mine, such as self-employed or non-resident buyers?
- What happens if the first bank declines my application?
A licensed broker with a wide panel adds the most value for buyers with complex income, tight budgets, or little time.
Digital Mortgage Platforms
Online platforms let you check eligibility, compare rates, and upload documents from your phone. For a simple salaried case, they can be fast and convenient.
They are less suited to complex profiles. A self-employed buyer with income from two companies, or an overseas buyer with foreign-currency earnings, often needs a human adviser who can explain the case to a bank’s credit team. If you use a platform, check who you will speak to when something goes wrong.
Developer Payment Plans: Not a Mortgage, but Often Compared to One
Off-plan developers often offer payment plans, including post-handover plans that spread payments over several years. These are not mortgages and are not regulated in the same way. Some carry no interest, but the property price may be higher to cover the cost. Many buyers still need a mortgage at handover to clear the remaining balance, so it pays to plan for that in advance.
How to Decide Which Type Fits You
- Simple salaried income and a strong bank relationship: check your own bank, but compare its offer against the wider market
- Preference for Sharia-compliant finance: speak to Islamic banks or a broker who offers Islamic options
- Self-employed, non-resident, or complex income: a broker or consultancy usually saves time and rejections
- Speed and convenience for a simple case: a digital platform can work, as long as you read the full terms
Whichever type of mortgage companies in Dubai you choose, always compare the total cost, not just the headline rate. Fees, insurance, early settlement terms, and the rate after the fixed period ends all affect what you really pay.
Related Blog Post : mortgage companies in dubai
Where Hateem Mortgage Fits In
Hateem Mortgage works as an adviser and broker, not a lender. The team compares conventional and Islamic options across its bank panel and explains how each offer is priced, so clients can make a clear decision.
Conclusion
Not all mortgage companies in Dubai are the same, and the difference affects your rate, your approval chances, and the advice you receive. Banks give you depth in one product range. Brokers give you breadth across the market. Digital platforms give you speed for simple cases. Choose based on your income type, your finance preference, and how much support you need, and you will start your property journey on the right footing.