Introduction
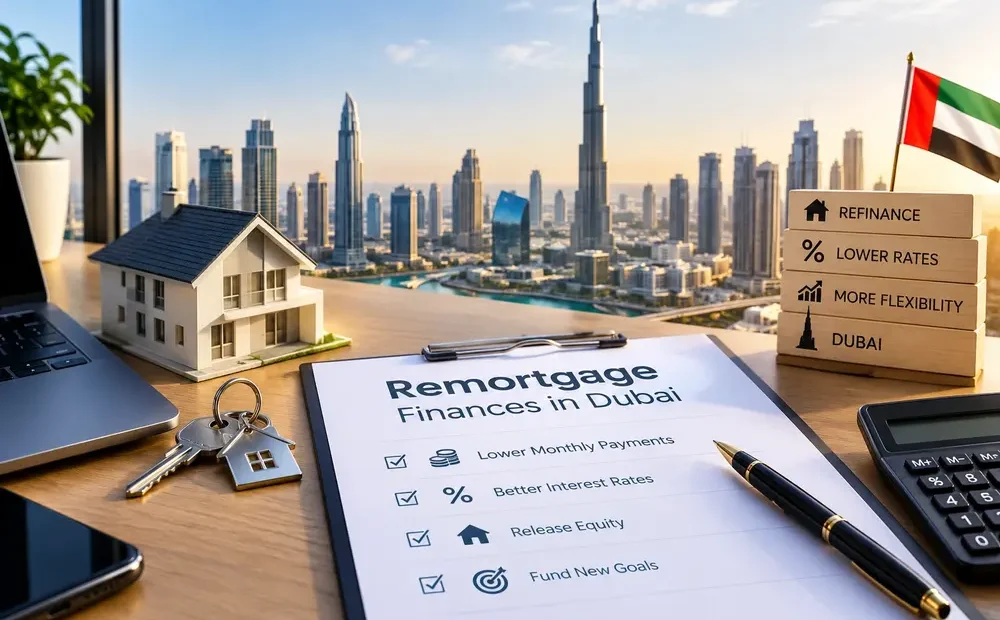
Many homeowners keep the same mortgage for the entire finance term simply because switching feels complicated. In reality, remortgage finances in Dubai give homeowners a straightforward way to move to a better rate, release equity, or change their repayment structure without selling the property. Understanding when remortgaging makes financial sense, what the process involves, and what costs to weigh against the potential savings helps homeowners decide whether switching is the right move at any given point in their mortgage term.
What a Remortgage Actually Involves
Remortgage finances in Dubai work by replacing an existing mortgage with a new one, either with the same bank or a different lender, based on the property’s current value and the outstanding balance owed. The new lender pays off the existing mortgage, and the homeowner begins making payments under the new finance’s terms. This is different from simply renegotiating with the current bank, since a remortgage opens the homeowner up to the full competitive market rather than being limited to whatever their existing lender offers to retain them.
The Main Reasons Homeowners Remortgage
The most common reason homeowners pursue remortgage finances in Dubai is to secure a lower profit rate than their current mortgage carries, particularly if the original finance was taken during a period of higher rates or if the initial fixed-rate period has expired and the finance has reverted to a higher variable rate. A second common reason is releasing equity — borrowing against the increased value of the property since purchase to fund renovations, another investment, or a major expense. A third reason is changing the finance structure itself, for example moving from a variable rate to a fixed rate for payment certainty, or extending the finance term to reduce monthly repayments.
Remortgage finances in Dubai are also used by owners who want to consolidate other debts into a single, lower-profit facility secured against the property, rather than continuing to service multiple higher-profit personal finances or credit card balances separately.
Costs to Weigh Against the Savings
Switching lenders through remortgage finances in Dubai is not free, and the costs need to be weighed against the expected savings before proceeding. Early settlement fees on the existing mortgage typically apply, often calculated as a percentage of the outstanding balance. The new lender will usually charge an arrangement fee and require a fresh property valuation. Mortgage registration with the Dubai Land Department also applies to the new finance. Homeowners should calculate the break-even point — how long it takes for the profit savings to outweigh these switching costs — before deciding whether remortgage finances in Dubai make sense for their specific situation.
Fixed Versus Variable When You Switch
Remortgage finances in Dubai also give homeowners a chance to reconsider whether a fixed or variable structure suits them better going forward. A homeowner who took the original mortgage on a variable rate during a period of low borrowing costs may now prefer the certainty of a fixed rate, especially if monthly budgeting has become tighter. Conversely, a homeowner nearing the end of a long-fixed period may choose to switch to another provider’s fixed offer rather than reverting to a standard variable rate, which is often priced higher than new-customer rates advertised in the market.
The Remortgage Process Step by Step
- Request a current settlement figure from the existing lender to confirm the exact outstanding balance and any early settlement charge.
- Compare remortgage finances in Dubai across multiple lenders based on rate, fees, and finance structure.
- Submit the application with updated income and identification documentation to the new lender.
- Arrange the property valuation required by the new lender.
- Complete the switch, with the new lender settling the old mortgage and registering the new one.
Most homeowners can complete this process within four to six weeks provided documentation is submitted promptly and the property valuation does not raise any issues.
Hateem Mortgage: Making the Switch Straightforward
Hateem Mortgage helps homeowners assess whether remortgage finances in Dubai are financially worthwhile in their specific case, running the break-even calculation, comparing offers across the full lender panel, and managing the settlement and registration process from start to finish. This removes much of the friction that otherwise discourages homeowners from switching even when a better deal is available.
Conclusion
For many Dubai homeowners, remortgage finances in Dubai offer a practical way to reduce borrowing costs, access equity, or restructure a mortgage to better suit changing needs. The decision comes down to weighing the switching costs against the expected savings over the remaining finance term. Hateem Mortgage provides the market comparison and process support that helps homeowners make that decision with confidence and complete the switch smoothly.